
Debt Snowball vs. Avalanche: Pick the Method You’ll Finish
Compare motivation and interest savings without losing sight of cash flow.
Start with a complete debt inventory
List every balance, annual percentage rate, minimum payment, due date, promotional-rate expiration, and whether the debt is secured. Pull statements rather than relying on memory. Include fees because a low stated rate can still be costly. Keep federal student loans separate from private loans because repayment protections may differ. Note any account already past due; preventing eviction, utility shutoff, repossession, or severe delinquency can outrank mathematical optimization.
How the avalanche works
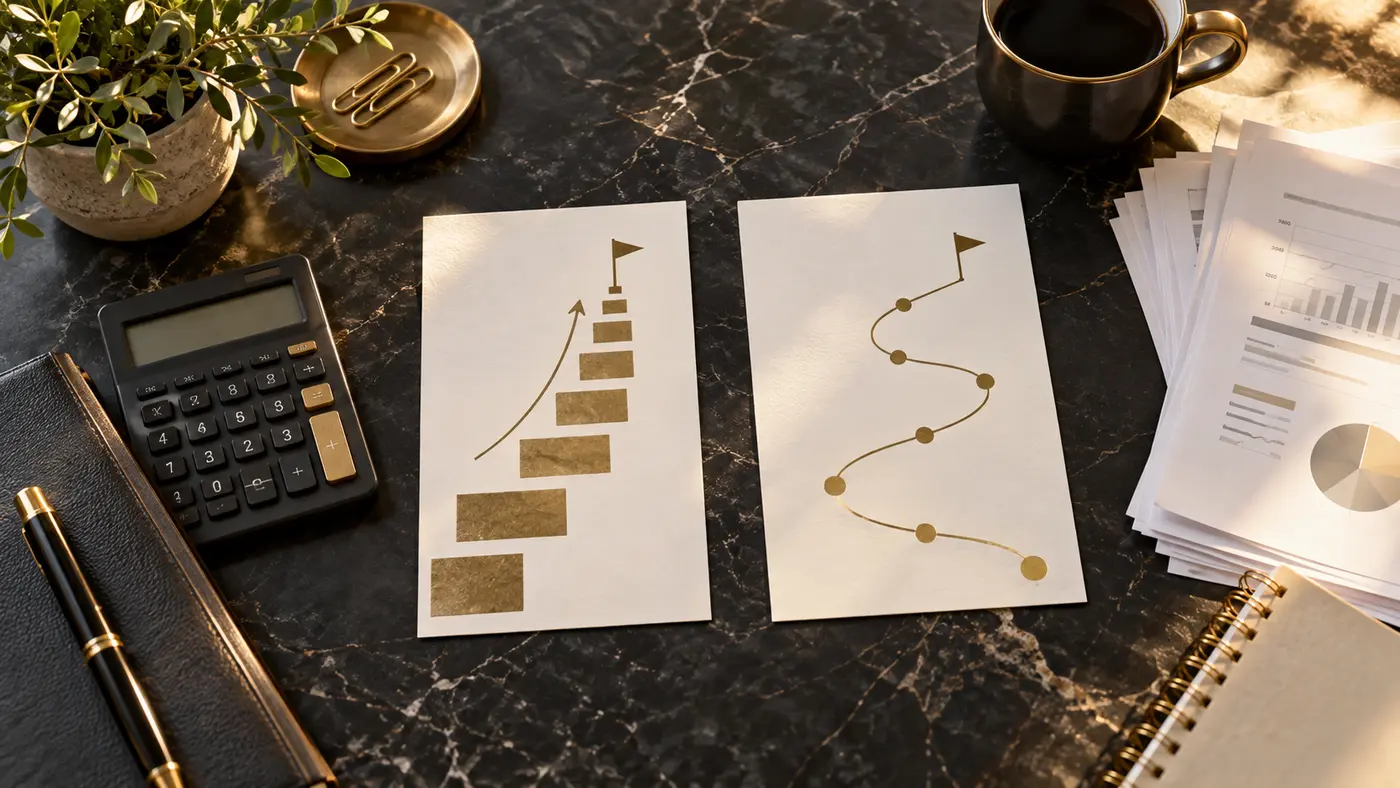
The avalanche method pays minimums on every debt and sends all available extra cash to the highest interest rate. After that balance is gone, its full payment rolls to the next-highest rate. Because it attacks the most expensive dollar first, it generally minimizes interest when balances, rates, payments, and timing are otherwise identical. For example, an extra $300 should usually go to a 24 percent card before a 7 percent loan. The savings are not mysterious: each $1,000 left at 24 percent costs roughly $240 a year before compounding and payment timing, versus roughly $70 at 7 percent.
How the snowball works
The snowball targets the smallest balance first regardless of rate. Eliminating an account can produce momentum and free a minimum payment quickly. Suppose three debts are $700 at 18 percent, $3,000 at 24 percent, and $12,000 at 8 percent. The avalanche chooses the $3,000 card; the snowball chooses the $700 balance. The snowball may cost more interest, but behavior matters. A plan that creates visible wins can outperform a cheaper plan that a person does not continue.
Compare the methods honestly
Use the same monthly budget for both scenarios and calculate payoff month and total interest. Do not compare an avalanche plan with $600 a month against a snowball plan with $450. If the cost difference is small, motivation can be a reasonable deciding factor. If it is large, consider a hybrid: eliminate one very small balance for momentum, then switch to the highest rate. Avoid treating either label as a moral identity. The goal is a repeatable payment system.
Protect cash flow while paying debt
Keep a starter emergency reserve so a tire, deductible, or urgent trip does not return to a card. Continue minimums through autopay when possible, then schedule the extra payment separately. Check whether extra payments are applied to principal and whether a loan has a prepayment penalty. If a promotional balance transfer is involved, calculate the transfer fee, required payoff payment, and rate after the promotion. A zero percent headline is not useful if the balance survives into a high-rate period.
When consolidation helps and when it does not
A consolidation loan can simplify bills and reduce interest if the new APR, fees, and term are genuinely better. A lower monthly payment created only by stretching the term can increase total interest. Moving unsecured debt against a home raises the stakes because the collateral can be lost. Debt settlement companies may charge fees and can involve missed payments, credit damage, collections, tax consequences, and lawsuits. Review alternatives with a reputable nonprofit credit counselor or qualified attorney when hardship is serious.
Common mistakes and an action plan
Common errors include paying extra before all minimums are covered, closing every paid card without considering fees and credit history, using retirement withdrawals without evaluating tax and penalty consequences, and continuing new card charges during payoff. This week, build the inventory, choose a fixed monthly payoff amount, select avalanche, snowball, or a documented hybrid, automate minimums, and schedule a monthly review. Send windfalls according to a rule chosen in advance rather than deciding after the money arrives.
Turn the information into a written decision
Before acting, write one sentence defining the decision: which balance receives every extra dollar and how large the fixed monthly payoff commitment will be. Then record the date, the numbers used, and the conditions that would make you reconsider. This short decision record prevents a common error: changing the goal after seeing an attractive product, frightening headline, or optimistic projection. Separate facts, such as a contractual rate or verified balance, from estimates, such as future returns, repair costs, or income. Mark each estimate as conservative, base, or optimistic. If the result works only under the optimistic case, the plan is fragile. A durable decision should leave room for ordinary error and should not require a favorable prediction to survive.
Build a source file
Collect current statements showing balances, APRs, minimums, due dates, fees, collateral, and promotional expiration dates. Use original statements, contracts, official releases, regulatory disclosures, and government data whenever possible. Save the publication or statement date because financial information becomes stale. For every number, note whether it is annual, monthly, nominal, inflation-adjusted, before tax, or after tax. Check that percentages use the same denominator and that comparisons cover the same period. A clean source file makes it easier to update the analysis, explain the decision to another household member, and spot a sales presentation that quietly changes assumptions.
Test the downside before accepting the upside
Run at least three cases: expected, uncomfortable, and severe but plausible. For this topic, test a missed overtime month, a rate reset, and a $1,000 emergency while the plan is underway. Do not simply reduce every number by the same percentage; ask which variables are linked and which could deteriorate together. Measure the effect on monthly cash flow, required reserves, total cost, and the date at which the plan stops working. Then identify a response for each failure point. A stress test is not a forecast and should not be presented as one. Its purpose is to reveal dependence on uncertain assumptions while there is still time to change the structure.
Use a pre-decision checklist
Confirm the goal and time horizon. Verify every material input from a primary document. Compare at least one realistic alternative, including the option to wait. Calculate both the monthly cash-flow effect and the longer-term total cost. Identify taxes, fees, penalties, liquidity limits, and collateral. Decide how much cash remains after the transaction. Name the biggest risk in plain language. Determine who benefits financially from the recommendation. Read cancellation, renewal, and adjustment terms. Finally, take a pause before signing when the decision is difficult to reverse. A checklist cannot guarantee a good outcome, but it reduces preventable errors.
Set a review date
Review the decision monthly and whenever a rate, income, minimum payment, or promotional term changes. A review should compare what actually happened with the original assumptions. Update inputs without rewriting the history of why the decision was made. If the outcome is worse than expected, determine whether the cause was bad luck, an incorrect assumption, a missing cost, or a behavior problem. That distinction improves the next decision. Avoid checking so frequently that normal volatility causes constant changes; also avoid setting a plan once and ignoring evidence that its foundation has changed.
Know when general education is not enough
Consider a nonprofit credit counselor, consumer attorney, or bankruptcy attorney before signing a settlement or placing secured property at risk. Ask how the professional is paid, what conflicts exist, which credentials or licenses apply, and whether the advice is limited to a product. Bring the source file and written questions. Professional help is most valuable when the law is local, the tax result is material, the contract is complex, collateral is at risk, or a mistake would be difficult to reverse. Education helps you ask better questions; it does not replace personalized analysis.
Concise takeaway
The avalanche usually saves more interest; the snowball may improve follow-through. The best plan protects minimums, preserves a small buffer, and uses a fixed payment until the debt is gone.
Sources and Further Reading
CFPB, Debt action planFTC, Coping with debtSources reviewed September 30, 2026. Check time-sensitive information at the linked source before acting.
 Personal Finance writer
Michael J. Carter
Personal finance editorial persona focused on cash flow, debt reduction, emergency planning, and durable money habits.
View Michael J. Carter's profileMichael J. Carter is a fictional editorial persona. This AI-generated portrait does not depict a real person. No professional license or credential is claimed.