
Bond Funds vs. Individual Bonds: Match the Tool to the Job
Compare ownership, income, maturity, diversification, costs, price risk, and reinvestment before choosing a fixed-income approach.
What you will learn
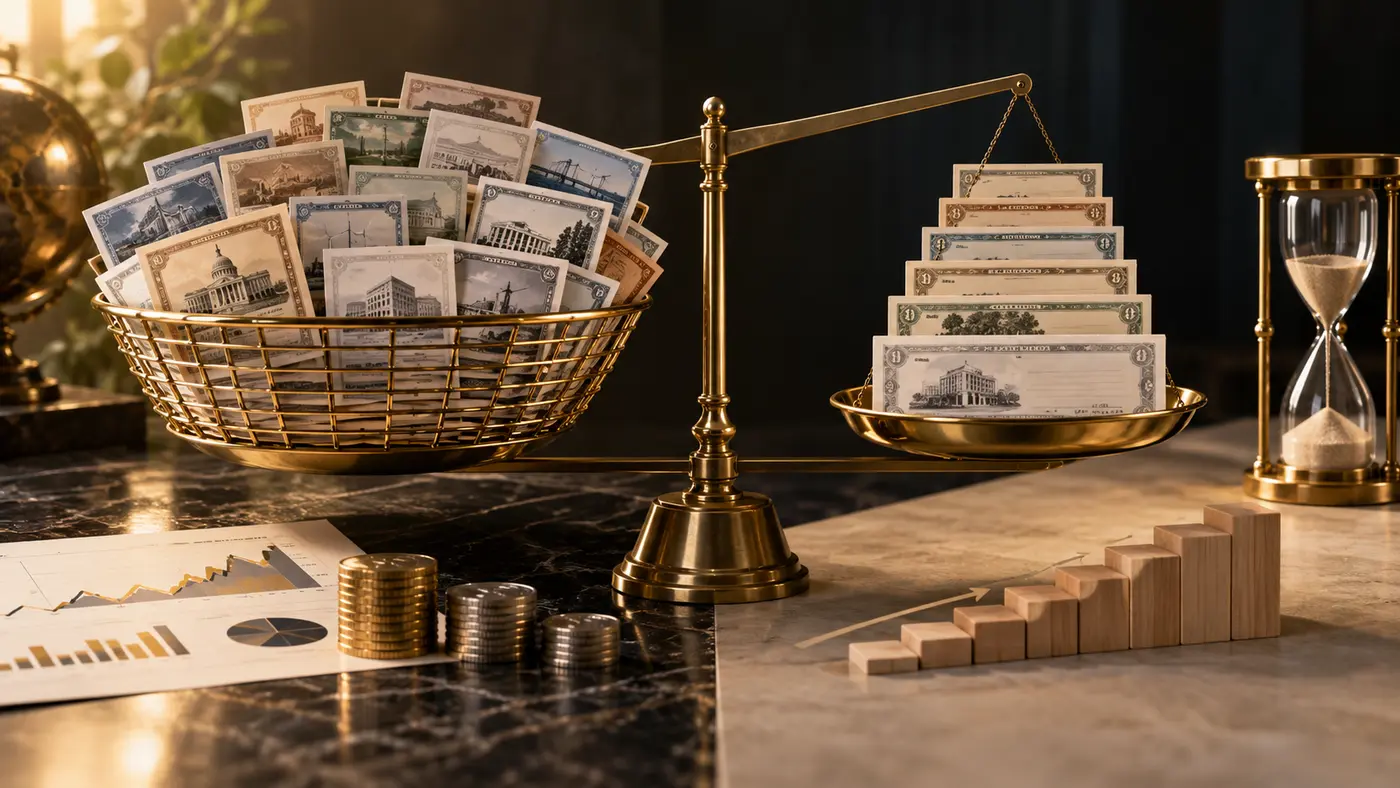
You will learn what you own in a bond fund versus an individual bond, how each may generate returns, which costs and risks remain, and how to research either choice through a brokerage or retirement account. The decision starts with the job the money must perform, not with a prediction about next month’s interest rates.
What an individual bond represents
A bond is a debt security: the investor lends money to an issuer, which promises interest and repayment according to contractual terms. Treasury securities are obligations of the U.S. government; municipal and corporate bonds depend on their issuers. If you hold a plain bond to maturity and the issuer pays as promised, you receive the stated payments and principal at maturity. That schedule can match a known future expense. But maturity does not eliminate risk. The issuer can default, a callable bond can be redeemed early, inflation can reduce purchasing power, and selling before maturity can produce a gain or loss. A quoted yield also depends on purchase price, coupon, maturity, and call assumptions.
What a bond fund represents
A bond mutual fund or ETF pools investor money and owns a portfolio of debt securities. You own shares of the fund, not a contractual right to receive the face value of one specific bond on a date you choose. A manager or index methodology buys, sells, and replaces holdings, so the portfolio generally maintains a target maturity or duration profile instead of maturing as a whole. Investor.gov notes that bond funds may hold government, municipal, corporate, mortgage-backed, convertible, or other debt. The share price or net asset value fluctuates. An ETF trades throughout the day and can deviate modestly from net asset value; a mutual fund normally transacts at the next calculated net asset value.
Where returns come from
Both approaches may generate interest income and price changes. For an individual bond, total return depends on coupon payments, purchase price, principal repayment, defaults or calls, reinvestment of income, and any sale price. For a fund, total return combines portfolio income, changes in the market value of holdings, realized gains or losses, expenses, and distributions. When market yields rise, existing fixed-rate bonds usually fall in price because newer securities offer more competitive income. Longer duration generally means greater price sensitivity. A fund does not “lose” the benefit of higher rates forever: over time, maturing holdings can be reinvested at higher yields. However, its share price is not guaranteed to return to a particular value on the investor’s chosen date.
Diversification favors funds—but inspect the portfolio
A broad bond fund may hold hundreds or thousands of securities, spreading issuer-specific default risk more efficiently than a small individual-bond portfolio. Diversification does not prevent losses from interest rates, inflation, widening credit spreads, mortgage prepayments, or market stress. Read the fund’s prospectus, summary prospectus, holdings, benchmark, duration, average credit quality, sector mix, and concentration. A high-yield corporate fund is not a substitute for a Treasury fund merely because both are called bond funds. Credit ratings are opinions, not guarantees, and averages can hide weaker holdings. With individual bonds, meaningful diversification can require substantial capital and careful analysis across issuers and maturities.
Maturity matching favors individual securities
An investor who knows that $20,000 is needed in three years may research a high-quality bond or ladder scheduled to mature near that date. The principal amount remains subject to issuer credit and transaction risks, but the contractual date can make planning more direct. A bond fund with a three-year duration is not the same as a bond maturing in three years; duration estimates price sensitivity and timing of cash flows, not a promise that the fund will deliver a fixed value on that date. For an ongoing retirement allocation with no single liability date, a diversified fund can be easier to maintain and rebalance. The correct comparison depends on whether the goal is a known payment or continuing portfolio exposure.
Costs are different, not absent
Bond funds charge an expense ratio, which reduces returns each year. ETFs may add bid-ask spreads and brokerage trading costs, though many platforms charge no explicit commission. Mutual funds can have sales loads, transaction fees, or account minimums. Individual bonds may appear commission-free because a dealer’s markup or markdown is embedded in the price. FINRA provides fixed-income trade data that can help investors compare recent transactions for many corporate and agency bonds. Small lots may receive less favorable pricing than institutional trades. Also consider the value of reinvestment, recordkeeping, diversification, and automatic contributions. A low visible fee is not proof of a low total cost.
Taxes and account location
Interest from taxable corporate bonds is generally subject to federal income tax and may be subject to state and local tax. Interest on U.S. Treasury securities is subject to federal tax but generally exempt from state and local income tax. Municipal-bond interest may receive federal or state tax advantages when requirements are met, but capital gains and alternative-minimum-tax considerations can apply. A fund passes through the tax character of distributions and may distribute gains; portfolio turnover and premium or discount purchases complicate results. In a tax-advantaged retirement account, current taxation may be deferred or avoided depending on account rules, but withdrawals have their own treatment. Tax-equivalent yield calculations require the investor’s actual marginal rates and the specific security; professional advice may be appropriate.
How to research and purchase
Start with goal, date, acceptable loss, liquidity need, and tax account. For a fund, search the ticker through the sponsor and SEC EDGAR, then read the current prospectus and shareholder report. Record expense ratio, benchmark, duration, yield definition, credit and sector mix, distributions, and trading characteristics. For an individual corporate or municipal bond, review issuer disclosures, maturity, coupon, price, yield to maturity, yield to worst, call schedule, credit information, minimum denomination, accrued interest, and recent trade data. Treasury securities can be bought through TreasuryDirect or a brokerage; other bonds usually trade through brokers. Use limit orders for ETFs when appropriate and understand settlement. Never buy solely from a yield ranking.
Risk scenarios and reasonable expectations
Test at least three scenarios. First, rates rise: longer-duration prices may fall, while future reinvestment opportunities improve. Second, rates fall: prices may rise, but callable bonds can be redeemed and future income may decline. Third, credit conditions deteriorate: lower-quality issuers and funds can fall even when Treasury yields move differently. A bond allocation may reduce volatility relative to stocks and provide income or liability matching, but it is unreasonable to expect no losses, a fixed fund price, perfect inflation protection, or stock-like long-term returns without added risk. Past yield and performance do not guarantee future results. Match the time horizon to duration and avoid funding a near-term essential expense with a portfolio that can fluctuate beyond the available margin.
A practical decision framework
Use individual high-quality bonds when specific cash needs and maturity dates dominate, provided you can evaluate credit, calls, pricing, and concentration. Research a broad, low-cost bond fund when diversified ongoing exposure, automatic contributions, and rebalancing matter more than a single maturity value. Combining them can also be reasonable: a ladder for known expenses and a fund for long-term allocation. Compare at least one alternative, including insured deposits or Treasury bills for short horizons and no bond exposure when the risk budget does not require it. The decision should survive without an interest-rate forecast.
Key Takeaways
An individual bond offers a contractual maturity subject to issuer and call risk; a bond fund offers ongoing diversified exposure with a fluctuating share value. Compare duration, credit, liquidity, costs, taxes, and the date the money is needed. Choose the structure that fits the job rather than chasing the highest displayed yield.
Sources and Further Reading
Investor.gov — Bond funds and income fundsInvestor.gov — Bonds and fixed-income productsInvestor.gov — Mutual funds and ETFsFINRA — Bond investing and due diligenceFINRA — Fixed Income DataSEC — EDGAR filings and fund disclosuresTreasuryDirect — Marketable Treasury securitiesSources reviewed October 15, 2026. Verify current prospectuses, prices, yields, tax rules, and issuer disclosures before investing.
 Investments writer
Marcus Lee
Investments writer focused on diversification, fund research, risk, costs, and evidence-based long-term decision making.
View Marcus Lee's profileMarcus Lee is a fictional editorial persona. This AI-generated portrait does not depict a real person. No professional license or credential is claimed.